Commercial valuation
How to value: Retail (storefront and plaza)
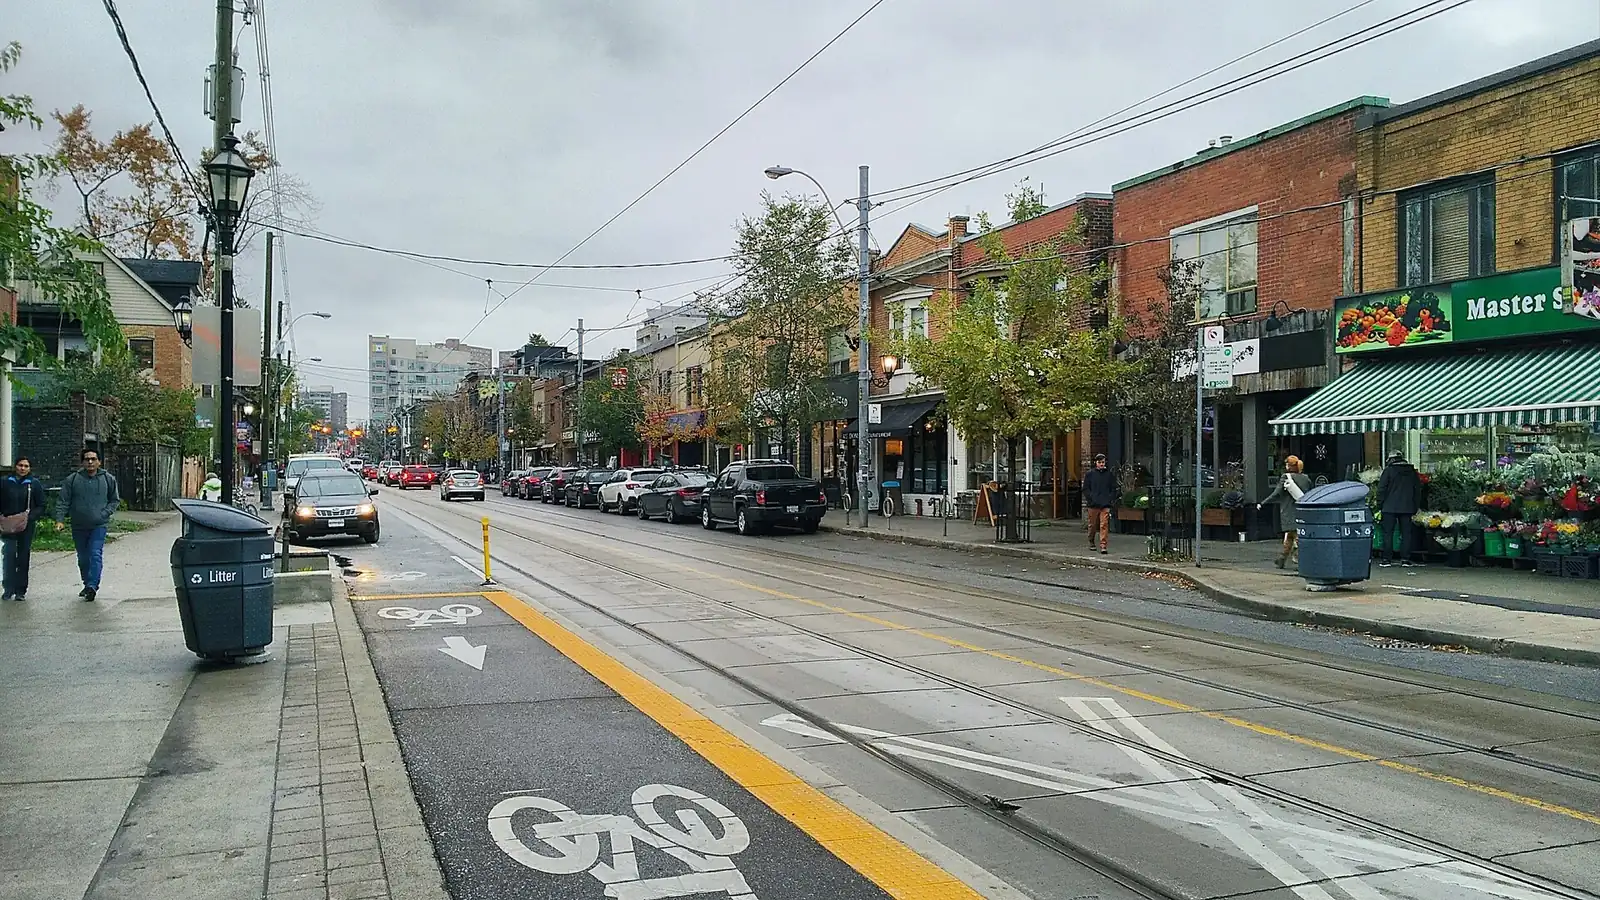
For a retail building, the rent tenants pay is the income, so the income approach is the main method. The same building can be worth very different amounts depending on who the tenants are and how long the leases last.
Main method
Income approach (NOI ÷ cap rate)
Check first
Tenant mix and lease expiries
Watch out for
Above-market rent and a large tenant leaving
Timing and the market The value of this type changes with the time and the market mood. Every number below is a made-up example, not a real market number.
How this type is valued
Take the total rent, subtract vacancy loss and the costs the owner pays, and divide the net operating income (NOI) by the cap rate. MPAC also says it values income-producing buildings such as shopping centres by the income approach.
The cap rate differs from building to building. Strong tenants and long leases are seen as lower risk. Weak tenants or leases that end soon are seen as higher risk. Higher risk tends to raise the return investors ask for (the cap rate).
Whether the leases are net leases (tenants share property tax and building operating costs) or gross leases (everything included in the rent) changes the owner’s costs and so the NOI.
For a single shop unit in a building, or a spot you will use for your own shop, comparing recent sales of similar units (direct comparison) is also used.
What drives the value
- Tenant mix: whether there is a large tenant (an anchor) that draws people in, and whether trades overlap.
- Lease length: whether many leases end at the same time.
- The gap between current rent and market rent: if the rent is above market, it may fall at renewal.
- Location, visibility (signs, street frontage), parking and foot and car traffic.
- Which trades zoning allows, and sign rules.
- The condition of the building and when big repairs are due (roof, parking lot).
Documents and numbers to check
- All leases and a rent roll (each tenant’s area, rent and lease term).
- Records of late rent and each tenant’s deposit.
- Income and operating costs for the last 2 to 3 years (property tax, insurance, upkeep) and the settlement of costs charged to tenants.
- The property tax bill and MPAC class.
- Operating permits and sign permits for each tenant.
- A building condition report and an environmental review (Phase I), especially if there was a dry cleaner or gas station.
What to watch out for
- A large tenant leaving and other tenants following.
- Leases ending soon with an uncertain renewal.
- Rent above the market that may fall at renewal.
- Operating costs that should be charged to tenants but are not collected, so the owner’s costs are larger than expected.
- Foot traffic that falls because of online shopping and new shops nearby.
A made-up example: the same plaza, a value that changes with the cap rate
These numbers are made up to show the arithmetic. They are not real market cap rates or prices. The example is one strip plaza with net operating income (NOI) of $240,000 a year.
| Cap rate | Net operating income (NOI) | Value |
|---|---|---|
| 5.5% | $240,000 | $4,363,636 |
| 6.5% | $240,000 | $3,692,308 |
| 7.5% | $240,000 | $3,200,000 |
What changes with timing and the market
- When rates rise, cap rates tend to rise and the value of the same NOI falls. (A general principle, not a rule.)
- When spending and the economy weaken, tenants’ sales drop and rent talks and closures can increase.
- In areas with many empty shops, finding a new tenant takes longer and perks such as free rent can grow.
- Even in the same area, new shops nearby or a big tenant arriving or leaving can change foot traffic.
- Do not treat the price of a similar plaza sold a few months ago as today’s value.
Official sources
What the official sources say 4
The valuation approach we use depends on a number of factors including property type, and the number of recent comparable sales of similar properties in the area.In plain wordsWhich method is used (direct comparison, income, or cost) depends on the kind of property and how many recent comparable sales there are. This page says MPAC uses the income approach for income-producing buildings. This is the property tax assessment method. It is similar to, but not the same as, how a market price is set.
Source: mpac.ca/en/UnderstandingYourAssessment/ThreeApproachesValue · checked Oct 30, 2026
This Act does not apply to tenancies and tenancy agreements to which the Residential Tenancies Act, 2006 applies.In plain wordsThe Commercial Tenancies Act (CTA) does not apply to tenancies that the Residential Tenancies Act (RTA) applies to. The RTA covers rental units where people live, so leases of commercial space such as shops, offices and warehouses are usually looked at under the commercial law rather than the RTA. Check mixed buildings with shops below and homes above separately.
Source: ontario.ca/laws/statute/90l07 · checked Nov 2, 2026
(iv) 2 per cent of the value of the consideration that exceeds $400,000; andIn plain wordsOntario land transfer tax is paid when the transfer of land is registered, and the part of the price above $400,000 is taxed at 2%. The extra 0.5% in the same section applies only to land with one or two single family residences, so for commercial and industrial land this 2% is the highest bracket. Toronto also has its own municipal land transfer tax, so ask a lawyer.
Source: ontario.ca/laws/statute/90l06 · checked Oct 30, 2026
A particular supply by way of sale of a residential complex or an interest in a residential complex made by a particular person who is not a builder of the complex or, if the complex is a multiple unit residential complex, an addition to the complex, unlessIn plain wordsThe exempt list includes the sale of a residential complex by someone who is not its builder. A sale of a commercial or industrial building or land does not fall under this item, so HST often applies. It depends on whether the seller is an HST registrant and how the buyer reports it, so check with an accountant.
Source: laws-lois.justice.gc.ca/eng/acts/E-15/page-120.html · checked Oct 30, 2026
FAQ
Does a good tenant raise the value?
Usually yes. A tenant with strong credit and a long lease is seen as lower risk, and a lower cap rate tends to apply. When the lease ends soon, the risk is seen as higher.
What is the difference between a net lease and a gross lease?
In a net lease the tenant pays some costs such as property tax. In a gross lease, one rent includes all the costs. See the glossary entry. With the same rent, the money left for the owner is different.
What if I buy one shop unit rather than a whole building?
Look at recent sales of similar units (direct comparison), and if it is rented, look at the rental income too. For a retail condo, check the condo fees, the rules and the reserve fund documents.
Other types
Restaurant
Restaurants, cafés and bars. Profit, lease terms and the liquor licence drive the value.
See details →
Vacant office
An empty office building or unit. Start from the value once leased, then subtract the cost of getting there.
See details →
Apartment building (multi-unit rental)
A building with several rental units. Rental income, operating costs and rent increase limits set the value.
See details →
Shall we look at the building you are considering?
Tell me about the property or business you are looking at and I will explain how it is valued and what to check first. A formal appraisal is done by a qualified appraiser.
This page was made from official sources checked on Nov 2, 2026. It is not legal, tax or financial advice.
Main sources for this page
- MPAC, Three Approaches to Value · Oct 30, 2026
- Commercial Tenancies Act (Ontario) · Nov 2, 2026
- Land Transfer Tax Act (Ontario) · Oct 30, 2026
- Excise Tax Act, Schedule V, Part I — exempt supplies of real property · Oct 30, 2026